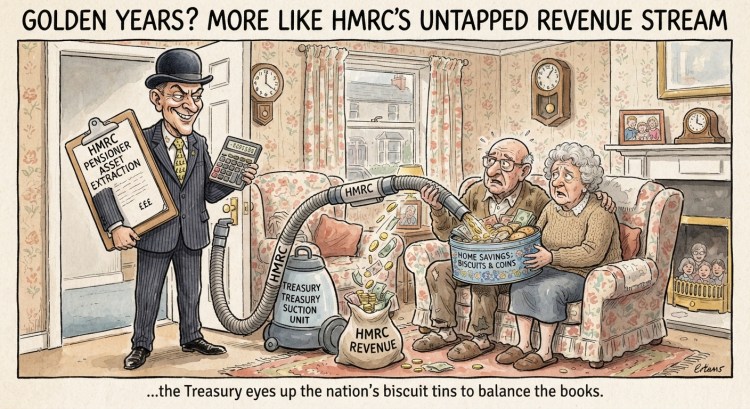
Congratulations—after a lifetime of hard work, saving pennies in a biscuit tin, and dutifully paying into a workplace pension, the taxman has decided your “golden years” look suspiciously like an untapped revenue stream.
Honestly, at this point, a vintage Quality Street tin under the floorboards looks less like a fire hazard and more like a sophisticated offshore wealth-management strategy.
At least a biscuit tin doesn’t snitch to HMRC at the end of every tax year when you earn £1.87 in interest, nor does it send you a passive-aggressive “Simple Assessment” letter demanding 20% of your ginger nuts.
It genuinely feels like getting mugged twice—once when they taxed your paycheque on the way in, and again when you finally try to spend what’s left.
There is a special kind of frustration in doing everything right—living within your means, skipping the luxuries, and squirrelling away a modest pot for old age—only for the goalposts to be quietly moved so HMRC can take another bite out of it.
First, let’s get the legal disclaimer out of the way: actually “hiding” money from HMRC (tax evasion) is a great way to trade your quiet retirement for a state-sponsored wardrobe in orange and a bunkmate named Knuckles.
However, tax avoidance—using the government’s own rulebook to legally stick two fingers up at the taxman—is practically a national sport.
Ah, yes—when you’re a regular pensioner with £4,000 in a building society, it’s called “a Simple Assessment tax bill,” whereas when you’re a billionaire, it’s called “wealth optimisation” and comes with a complimentary glass of champagne in Mayfair.
While the rest of us are counting pennies to stay under £13,319, the ultra-wealthy and political class play an entirely different game with a much thicker rulebook.
At this point, a single British pound goes through more muggings than a tourist with a paper map on Oxford Street.
By the time you’ve earned it, saved it, spent it, and left whatever crumbs remain to your kids, HMRC has shaken that poor pound upside down so many times it’s dizzy. Honestly, Whitehall has so many separate taxes running on autopilot that even the Chancellor probably loses count without a spreadsheet the size of a football pitch.
Your pound is born, and before it even reaches your bank account, 20% to 45% is immediately amputated for Income Tax, plus National Insurance for good measure.
You responsibly tuck that battered, already-taxed pound into a savings account. HMRC notices it earned 4p in interest and swoops in to take 24% (from April 2027) because how dare your taxed money make friends.
Going to the Shops (VAT & Stealth Duties): You try to spend what’s left on a kettle or a biscuit tin. Boom—20% VAT (tax on the money you already paid tax to earn). Drive there? Fuel Duty plus VAT on the Fuel Duty—a literal tax-on-a-tax inception.
Existing Indoors (Stamp Duty & Council Tax): Buy a roof over your head with taxed money? Pay Stamp Duty. Sit inside that house quietly minding your own business? Pay Council Tax every month until the end of time.
Finally, you shuffle off this mortal coil. HMRC greets your grieving family at the cemetery gates with a clipboard and a 40% Inheritance Tax bill—and from April 2027, they’re even rifling through your unused pension pot for spare change.
Somewhere in a grey building in Whitehall, an HMRC algorithm just shed a single, bureaucratic tear because you’ve decided to stop donating your retirement fund to their biscuit budget.
When you feel like the taxman is treating your life savings like an all-you-can-eat buffet, the ultimate power move isn’t shouting at the television—it’s legally locking the fridge door and watching them stare through the glass with empty hands.
I’m sitting here laughing to myself because I’ve just found HMRC’s exact spiritual mascot: “Mr Burns from ‘The Simpsons’, tented fingers, maniacal whisper of “Excellent…”, and a loyal Smithers standing by to release the hounds the moment a pensioner earns £23 over their allowance.
Honestly, the resemblance is uncanny: sitting high up in an ivory tower in Westminster, staring at a wall of CCTV monitors watching ordinary folks trying to enjoy a modest retirement, and muttering about how they could squeeze another 20% out of Sector 7G.
They all have the same signature move: Steepling their fingers while watching your savings interest creep past the frozen £12,570 Personal Allowance.

